

As businesses seek to expand in an increasingly competitive economy, access to affordable capital remains one of the biggest barriers to growth. From purchasing commercial vehicles and agricultural machinery to investing in manufacturing equipment and renewable energy solutions, many enterprises struggle with the high upfront costs of acquiring productive assets.
According to Gloria Ssuuna Namutebi, Head of Vehicle and Asset Finance at dfcu Bank, asset financing is increasingly enabling businesses to invest in growth while preserving the working capital needed for day-to-day operations.
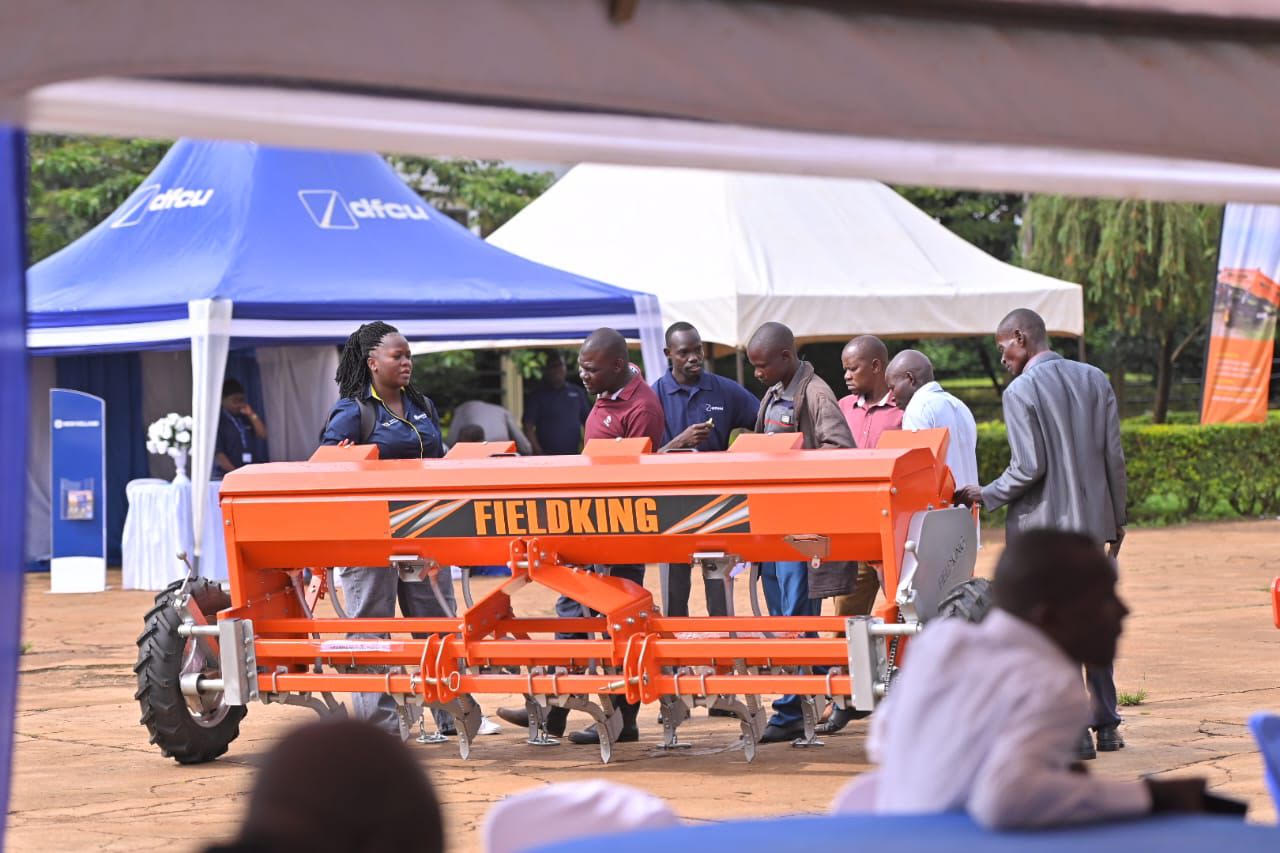
Speaking in an interview, Ssuuna said dfcu’s Vehicle and Asset Finance proposition extends far beyond vehicle loans, providing financing for a wide range of productive assets including tractors, construction equipment, medical machinery, manufacturing plants, solar installations and commercial vehicles.
She explained that the financing solution allows businesses to acquire critical assets immediately and repay over time in line with their cash flows, eliminating the need for large upfront capital outlays. The facilities are available to salaried individuals, sole proprietors, SMEs, corporates, partnerships, investment clubs and women-owned businesses, with financing ranging from UGX 1 million to over UGX 15 billion, depending on the customer’s needs and financial profile.
Ssuuna noted that dfcu finances both new and used passenger vehicles, trucks, buses, agricultural machinery, irrigation systems, generators, printing equipment, milk coolers and other movable, identifiable and insurable assets. She said the bank structures financing differently for each sector, recognising that farmers, contractors, manufacturers, hospitals and schools all have unique business cycles and financing requirements.
On affordability, she said qualifying customers can access financing of up to 90 percent for new assets and 80 percent for used assets, while selected customers may qualify for 100 percent financing, subject to assessment. Repayment periods range between 12 and 84 months, with repayment schedules tailored to match customers’ income streams, particularly for sectors such as agriculture where earnings are seasonal.
She highlighted several strategic partnerships that have expanded access to asset finance, including collaborations with Double Q, ICEA LION, Meta Plant & Equipment Uganda, and World Navi Company Limited.
According to Ssuuna, the partnership with Double Q and ICEA LION combines financing, vehicle supply, insurance, maintenance, warranties and technical support into one integrated solution, while also promoting the adoption of electric and hybrid vehicles. Meanwhile, the partnership with Meta Plant & Equipment enables farmers to access agricultural machinery with repayment plans aligned to seasonal harvests, alongside regional after-sales servicing.
She added that dfcu’s collaboration with World Navi Company Limited provides customers with a safer and more transparent process for importing quality used vehicles from Japan, complemented by financing, insurance, warranties and repayment periods of up to seven years for eligible vehicles.
Ssuuna encouraged businesses to view asset finance as a strategic capital management tool rather than simply borrowing. She explained that preserving cash for operational expenses such as salaries, inventory and fuel often creates greater value than using all available funds to purchase an asset outright.
“Asset finance works best when the financed asset generates income that contributes towards its own repayment while allowing the business to maintain sufficient liquidity for operations and future growth,” she said.
She noted that the application process begins with the customer obtaining a pro forma invoice from the supplier before submitting proof of income and financing documents for assessment. Where all documentation is complete and the asset is readily available, approvals and disbursement can take about 15 working days.
Ssuuna further explained that the financed asset itself serves as security in most cases through a chattel mortgage, eliminating the need for additional collateral unless the customer’s risk profile requires it. She added that newly established businesses may also qualify if they can demonstrate reliable income through verifiable contracts or other sustainable revenue sources.
She advised business owners to carefully evaluate how an asset will improve productivity, reduce costs or generate additional revenue before taking financing, emphasizing that repayment obligations should always be supported by projected cash flows.
Ssuuna concluded that as Uganda’s economy continues to grow and businesses increasingly invest in mechanisation, transport and technology, flexible asset financing will remain a key driver of enterprise expansion, productivity and sustainable economic development.