

OPINION (UGNEWSLINE) – Uganda’s next phase of economic transformation will not be determined simply by how much capital the country can mobilize, but by where that capital flows, what it finances and what it ultimately enables.
The Ugandan economy has given us reason for confidence. Growth has held at a strong pace, estimated at around 6.3 to 6.4 percent in both FY 2024/25 and FY 2025/26, and private-sector credit continues to expand. But growth and credit volumes alone do not tell us whether financing is reaching the businesses that will define Uganda’s next decade.
Bank of Uganda data show commercial-bank shilling lending rates sitting in the high teens, reported at around 18.9 percent in April 2026, with some easing since. At that cost, financing struggles to reach investments whose returns are measured in years rather than months. The real debate is not only how much credit is available, but what it enables, and whether it can be made affordable and patient enough for investments that build lasting capacity.
Agriculture is the clearest example. Uganda already produces in abundance; the economic gains that matter now come from processing what we grow rather than exporting it raw. That means financing irrigation and modern farming equipment, post-harvest storage and cold-chain infrastructure, agro-processing plants, packaging, transport and logistics, export-oriented agribusiness, and the technology that builds climate resilience into farming. The central question is where capital can best help Uganda shift from producing raw commodities to producing higher-value goods.
Manufacturing tells a related story. The priority must be capital expenditure and patient financing that expand productive capacity rather than fund immediate consumption: machinery and technology upgrades, industrial parks, local supply chains, working capital for manufacturers, export manufacturing, and support for the SMEs that supply larger industrial players.
SME financing deserves a reframe of its own. It is easy to describe SME lending as simply ‘lending to small businesses.’ It is far more useful to think of it as financing the next generation of employers. Many businesses are not short of ideas or markets; they are constrained by insufficient working capital, short loan tenors, limited collateral, informality, weak financial records, an inability to finance equipment, and difficulty breaking into larger supply chains. Solve for these constraints, and the multiplier effect on employment is significant.
All of this relies heavily on productive infrastructure. Businesses become truly competitive when energy, transport, logistics, digital networks, water, industrial facilities, warehousing, and urban infrastructure are reliable enough to build on. This is where blended capital holds the greatest potential, with government, development finance institutions, commercial banks, and institutional and private investors each taking on a distinct layer of risk.
Finally, green and climate-resilient investment is no longer a future consideration. The question is not whether Uganda will need it, but whether capital will reach businesses early enough for them to adapt. Renewable energy, energy efficiency, climate-smart agriculture, waste management, green manufacturing, and resilient infrastructure all compete for the same pool of financing.
At DTB, our experience working with businesses across agriculture, manufacturing, tourism, and other sectors reinforces a simple lesson: financing has the greatest economic impact when it helps a business acquire productive assets, enter a new market, increase capacity, or connect to a larger value chain.
Banks are already seeing where the primary bottlenecks lie. Tenors remain short relative to what productive investment requires, risk perception weighs heavily against sectors like agriculture and manufacturing, collateral requirements exclude viable businesses, and informality makes underwriting harder than it should be. These are solvable problems, and solving them should guide what comes next.
Four shifts would help. First, move from short-term lending to patient capital where the underlying investment justifies it. Second, crowd private capital into national priorities rather than leaving government and development finance institutions to carry the risk alone. Third, finance businesses rather than just balance sheets by looking at their capacity to grow instead of collateral on hand. Fourth, measure financing success by economic outcomes, jobs created, productivity raised, and value added, rather than simply the volume of credit disbursed.
Uganda’s next phase of growth will not be determined simply by how much capital we mobilize, but by where we choose to put it. Agriculture with value addition, manufacturing, high-potential SMEs, productive infrastructure, and climate-resilient investment are where that capital will do the greatest good. Capital should always follow productivity, value addition, job creation, and export potential.
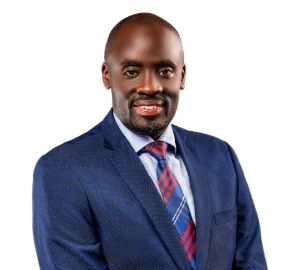
The author is Kaziro Kyambadde, the Head Corporate Institutional and Business Banking at DTB Uganda